Stablecoin and The Genius Act

Stablecoin Market Surpasses $250 Billion as Institutional Adoption Accelerates


August 2025 — The global stablecoin market is undergoing a transformative shift, with its market capitalization surging past $250 billion, according to recent financial data and institutional analyses published throughout July and August. The growth reflects increasing institutional usage, expanded utility in global payments, and a more defined regulatory framework that appears to be bolstering confidence among issuers and users alike.


Stablecoins, digital assets pegged to fiat currencies such as the U.S. dollar, have emerged as a key segment of the broader cryptocurrency ecosystem. Unlike more volatile digital assets, stablecoins are designed to maintain a fixed value, which has made them particularly attractive for use in everyday transactions, cross-border remittances, and institutional operations.


Institutional Usage Reaches New Highs


A July 2025 report from Fireblocks, a digital asset infrastructure platform, revealed that 90% of surveyed financial institutions are either currently using stablecoins or exploring their use in daily operations. Of these, nearly half—46%—have already integrated stablecoins into their payment flows, while another 23% are conducting pilot programs to evaluate operational viability.


The trend is driven by a combination of efficiency, lower transaction costs, and improved settlement speed. As stablecoins reduce the need for intermediaries and allow for real-time fund transfers, institutions are increasingly viewing them as superior alternatives to traditional payment rails.


Transaction Volumes Surpass Visa and Mastercard Combined


Stablecoins are not just being used—they are dominating. In 2024, the total transaction volume processed through stablecoins exceeded that of both Visa and Mastercard combined. This benchmark underscores the rapid mainstreaming of digital currencies and highlights how stablecoins are positioning themselves as serious contenders in the global payment infrastructure.


Cross-border payments, often burdened by high fees and multi-day settlement times, are among the most immediately disrupted areas. In regions with limited banking infrastructure or capital restrictions, stablecoins offer a streamlined method to move funds internationally with lower friction and cost.


U.S. Regulatory Clarity Boosts Confidence


A pivotal moment in the stablecoin sector came with the passage of the GENIUS Act in July 2025. The legislation introduced a clearer regulatory framework for the issuance and operation of stablecoins in the United States. Most notably, it mandates full 1:1 reserve backing for fiat-pegged stablecoins, ensuring that each token issued is fully backed by an equivalent amount of fiat currency or equivalent high-quality liquid assets.


The law also introduces federal oversight mechanisms for stablecoin issuers, with periodic audits and disclosure requirements designed to prevent risks to financial stability. This move has been broadly welcomed by market participants and institutional stakeholders, many of whom had previously expressed concerns about the lack of regulatory oversight and risk exposure.


Analysts expect the GENIUS Act to act as a catalyst for further institutional entry into the stablecoin market, especially from banks, payment processors, and fintech firms that had previously remained on the sidelines due to regulatory uncertainty.


Tether and USDC Lead, But New Issuers Emerge


Currently, Tether (USDT) and USD Coin (USDC) remain the dominant players, representing a substantial share of the stablecoin market capitalization. Both have benefitted from early mover advantages, wide exchange support, and strong liquidity.


However, the landscape may not remain static. The introduction of regulatory clarity and increasing interest from traditional financial institutions suggest that new entrants, including commercial banks and multinational corporations, may soon begin issuing their own compliant stablecoins. These entrants could reshape competitive dynamics, especially if they bring existing customer networks and infrastructure to the table.


Challenges Ahead


Despite the optimism, stablecoins face several challenges. Ensuring liquidity during market volatility, mitigating counterparty risks in custodial relationships, and navigating a patchwork of global regulations remain top concerns. The GENIUS Act may serve as a template, but regulatory harmonization across jurisdictions is still a work in progress.


Furthermore, as stablecoins become more embedded in financial systems, questions about monetary policy implications, systemic risk, and consumer protection will likely become more prominent.


Looking Forward


The stablecoin market is poised for continued expansion and deeper integration into traditional finance and commerce. Its success in 2024 and 2025 demonstrates not only a maturing digital asset class but also a wider institutional acceptance of blockchain-based financial tools.


As stablecoins become more embedded into global financial infrastructure, they have the potential to revolutionize payments, democratize access to financial services, and streamline international commerce. The next phase of growth will depend on the sector’s ability to scale securely, remain compliant, and meet the evolving demands of both institutional and retail users.


The trajectory suggests stablecoins are no longer a fringe innovation—they are becoming foundational components of the digital financial future.


Risks: While stablecoins aim to maintain a stable value, they are not without risk. They can lose their peg to the underlying asset, and their value can be affected by factors like regulatory changes or the solvency of the issuer. For example, in 2022, the algorithmic stablecoin TerraUSD fell to $0.12. In 2023, both USDC and DAI depegged due to the failure of certain US banks, although they later recovered.

After dipping a curious toe into the crypto market story, I am at this point neither convinced or resistant. I have concerns that cryptocurrency may fall victim to online attacks or a massive internet failure that might separate us from access to our cash. However, as quiet as it’s kept, if it’s not in your pocket – your cash in an ATM is subject to similar failures. The point is, “if you know – you know”. Congratulations, because you don’t know what you don’t know, and now is the time to find out.


Want to learn a little something? How about a FREE class. I’ll go and let you know…


Sign up for a free trading and investing workshop | Trading Academy

https://share.google/13LC4mnvRwMTtb2fL


Dana Meyers RIH

Legendary Songwriter and A&R Executive Dana Meyers Found Deceased in Pasadena Home


PASADENA, Calif. — July 28, 2025


Dana Meyers, a celebrated songwriter, producer, and longtime figure in the soul and R&B music community, was found unresponsive in his Pasadena apartment on Sunday. He was 73.


Meyers, born April 15, 1952, in Dayton, Ohio, rose to prominence during the late 1970s and early 1980s, becoming a key contributor to the “Sound of Los Angeles Records” — better known as SOLAR Records. He played a critical role in crafting the smooth funk and dance-infused soul music that came to define the era, collaborating closely with producer Leon Sylvers III.

According to authorities and local media reports, Meyers had not been seen in public since hosting a well-attended reunion picnic for SOLAR Records and Soul Train alumni the previous weekend. Neighbors and friends expressed concern after several days passed without communication, but the latest update claims that he was in distress and passed during a hospital visit.

Meyers’ legacy in the music industry is deeply rooted in his work with SOLAR Records’ most iconic acts. He was instrumental in writing and arranging a string of chart-topping singles and album cuts for artists such as The Whispers and Shalamar. His compositions helped define a golden era of Los Angeles soul and R&B, blending tight vocal harmonies with upbeat grooves and synthesized funk elements.


The Whispers, one of the most successful vocal groups under the SOLAR banner, recorded several hits co-written by Meyers. His songwriting contributions helped solidify the group’s commercial success during the early 1980s. Similarly, his work with Shalamar — known for its dance-floor anthems and smooth, stylish aesthetic — played a central role in elevating the group to international stardom.


Beyond his songwriting talents, Meyers was known in the industry as a meticulous arranger and thoughtful mentor. His transition into Artist & Repertoire (A&R) management allowed him to guide younger generations of talent. For the last several years, he served in that role for SOLAR RecordsUK, the label’s revived and rebranded international branch. In this position, he maintained ties to the label’s founding ethos while expanding its reach across the Atlantic.


“He understood what made a song stick — the feeling, the groove, the truth in the lyrics,” said one colleague on social media. “He never stopped believing in the power of soul music.”


Meyers’ last public appearance was the aforementioned reunion picnic, which drew former artists, producers, dancers, and executives who had once been part of the vibrant SOLAR and Soul Train scenes. Attendees shared photos and videos on social media, celebrating a day filled with music, storytelling, and community. Many expressed gratitude for Meyers’ role in organizing the event and described him as being in good spirits, laughing and sharing memories with old friends.

Reactions to the news of his passing have been swift across social media, particularly from within the Black music community, with numerous artists and fans reflecting on his quiet but profound influence. Some noted that his name may not be widely known to the casual listener, but his songs — and the feelings they evoked — have long been part of the cultural fabric.


Meyers began his musical journey in his hometown of Dayton, a city known for producing a rich lineage of funk and soul talent. His career later brought him to Los Angeles, where he found a creative home at SOLAR, whose innovative approach to artist development and sound curation made it one of the most influential independent labels of its time.


In addition to his work behind the scenes, Meyers occasionally recorded and performed as an artist, with several tracks achieving cult status among fans of classic R&B and boogie funk. His layered production style, ear for melody, and commitment to authenticity earned him respect from both his peers and the artists he supported.

As a fledgling entertainer, back in the late 60s and early 70s, he performed with Dayton singing groups, The Emeralds, the 4 Corners, the Bad Bunch, Platypus, Lakeside and a bunch of start-up bands. I even had a chance to sing alongside him in a Los Angeles club, where he broke out his signature AXE, the Auto-Harp.


As an A&R manager, Meyers was known for encouraging innovation while preserving musical integrity. Under his guidance, several new projects for SOLAR RecordsUK were in development, reflecting a continued commitment to showcasing talent rooted in tradition but forward-looking in sound.


Dana Meyers leaves behind a daughter, a grandchild and a legacy that spans nearly five decades, marked by a devotion to music that moved people — whether through love ballads, dance tracks, or socially conscious songwriting. In a world of changing trends and fleeting fame, he remained a steady force behind the scenes, crafting moments that mattered.


Funeral and memorial arrangements have not yet been announced. Colleagues, family, and fans are expected to gather in the coming days to honor a man whose songs — and spirit — left an indelible imprint on the sound of a generation.


Inglewood Beat

Leah C: A few nights ago, my dog started barking at about 2:00 am. This is the 400 block of W. Hillsdale. My security camera ccaptured a coyote approaching my front door at 1:56. Please ensure your pets are kept indoors at night.

●

Charles Received this letter:  “We want to let you know about an upcoming change happening at the The CHASE branch at 5309 W. Centinela Ave. in Los Angeles is closing on October 23, 2025.

The Chase team at 8813 S. Sepulveda Blvd. in Los Angeles is ready to welcome you. (Near Petco) (this is not the Culver City Branch, adjacent to the Mall.)

●

IN THE NEWS:  Charges Have Been Dropped Against Activist Who Gave Out Face Shields During the LA Protests.

●

ROBERT: Reports in the neighborhood.

Tire stealing has been happening often. I also was a victim as well as my neighbors. I encourage everyone if possible, “place locks on tires and every lugs. Hate this is even happening but stay vigilant.”

Breast Cancer Legislation

VERY IMPORTANT LEGISLATION 

Congresswoman Maxine Waters Introduces Landmark Legislation to Improve Breast Cancer Treatment and Recovery Access


Washington, D.C. – July 24, 2025 — Congresswoman Maxine Waters (CA-43), a senior member of the U.S. House of Representatives and Ranking Member of the Financial Services Committee, introduced two major health-focused bills designed to eliminate disparities in breast cancer treatment and ensure all women have access to comprehensive care and recovery services. The proposed legislation, H.R. 4543 – the Medicaid Breast Cancer Access to Treatment Act and H.R. 4545 – the Medicare Breast Reconstruction Access and Information Act, addresses systemic gaps in coverage and patient education across federal healthcare programs.

 

Waters has been an unwavering advocate for breast cancer patients for over four decades. Her efforts date back to her tenure in the California State Assembly, where in 1978 she successfully championed AB 3548—legislation mandating insurance coverage for prosthetics or reconstructive surgery following mastectomies. These latest federal initiatives build on that legacy and aim to address longstanding inequities in treatment access, particularly among low-income and underserved populations.


“I am deeply concerned about the tragic and unacceptable disparities related to breast cancer,” Waters stated. “That is why I introduced the Medicaid Breast Cancer Access to Treatment Act, which requires all state Medicaid programs to cover breast and cervical cancer treatment services for low-income patients with no cost-sharing.”


This legislation also mandates Medicaid coverage for breast reconstruction surgery after a medically necessary mastectomy—a procedure many low-income women currently cannot afford or access.


The second bill, the Medicare Breast Reconstruction Access and Information Act, tackles the issue of informed consent and patient knowledge regarding surgical options. Waters noted a troubling pattern: numerous breast cancer survivors across the country have undergone mastectomies without fully understanding that Medicare covers reconstruction services. H.R. 4545 seeks to rectify this by requiring surgeons and healthcare providers to inform Medicare patients about their post-surgical options.

“Patients who receive thorough information are more likely to make informed decisions that align with their individual preferences,” Waters emphasized. “This leads to greater satisfaction and an improved quality of life following surgery.”


Breast cancer remains the most frequently diagnosed cancer among women in the United States, accounting for approximately 30% of all new cancer diagnoses each year. Although death rates have dropped 44% since the 1980s due to advances in screening, early detection, and treatment, disparities in outcomes persist. According to national health data, Black women are 40% more likely to die from breast cancer than non-Hispanic white women. These disparities are often tied to delayed diagnoses, lower access to advanced treatments, and gaps in insurance coverage.


Many patients from lower-income communities, including those reliant on Medicaid, face serious hurdles when seeking treatment for breast cancer. Some are forced to forgo reconstruction entirely due to a lack of coverage, while others are never made aware that such options exist. The situation is further complicated by inconsistent policies across state Medicaid programs and insufficient provider communication.


Through these two bills, Waters and a broad coalition of House Democrats are aiming to bring greater equity and consistency to breast cancer care across the U.S. healthcare system.


Both H.R. 4543 and H.R. 4545 have gained the backing of more than two dozen co-sponsors, including Representatives Debbie Dingell (MI-06), Terri Sewell (AL-07), Marc Veasey (TX-33), Rashida Tlaib (MI-12), and Frederica Wilson (FL-24), among others. The breadth of support spans from California and Florida to Maryland and Massachusetts, reflecting a nationwide concern over health care disparities.


Local and social media platforms have reflected strong support for the measures, particularly among breast cancer advocacy groups and women’s health organizations. Online discussion has highlighted the urgency of reducing financial barriers to care and promoting patient-centered approaches that prioritize information and choice.


Community health forums in urban areas, including parts of Los Angeles and the Northeast, have echoed Waters’ concerns, with survivors and advocates emphasizing that education, transparency, and access must go hand-in-hand for truly equitable care. Social media users have also drawn attention to the emotional and psychological toll of breast cancer treatment, stressing the value of reconstructive options in restoring body image and confidence.


“Together, these two bills will help ensure that all breast cancer patients—regardless of income or insurance status—have access to the full spectrum of care,” said Waters.


The bills now await further consideration in the House, with supporters hoping to bring them to a vote during the current legislative session. If passed, the legislation could mark a transformative step in the fight against breast cancer and a significant expansion of rights and resources for patients navigating one of life’s most difficult diagnoses.


Full list of Supporters

https://1man1vote.com/wp/?page_id=916


The More Things Change

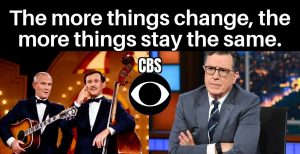
Let us not forget that Television is one part broadcasting, one part advertising and one part programing.

CBS canceled The Smothers Brothers Comedy Hour in 1969, “officially” citing their failure to meet contractual pre-air delivery dates for episodes. (a purely business decision) However, the true reason was the ongoing conflict with the network over the show’s controversial political satire and social commentary, particularly regarding the Vietnam War and civil rights.

So, Which Is It?

So which is it?

Skins

No DEI or all DEI. Demanding that all naval ships, military installations, and now sports teams, be stripped of their DEI designations and be named only after good clean white folk, seems to be either reverse DEI or plain and simple white supremacist racism. Even more concerning and sinister is his new demand that, under threat of executive prerogative to F with their money, all teams should revert back to their (for simplicity sake let”s just call it) “slave names”.

With what is allowed to go for clear eyed vision, it becomes clear that he strives to intentionally, and brutally deliver on Manifest destiny, by forcing native Americans to just live with the indignity of those naming conventions. Once again for his own amusement, under the guise of electoral mandate, he does not shy away from any opportunity to “hurt someone and help no one.”

###


capitulation

[kuh-pich-uh-ley-shun]

noun

the act of capitulating.

1. the document containing the terms of a surrender.


Play Ball


Getting High In America

In the late 1800s, Chinese immigrants in the United States, particularly on the West Coast, were heavily associated with the opium trade and the operation of opium dens. While not all Chinese immigrants were involved in this trade, opium use and sales became a prominent part of some Chinese communities, especially in places like San Francisco’s Chinatown.

Opium dens, often described as hidden and underground spaces, were typically run by Chinese men and became gathering places for smoking opium, These dens, sometimes adorned with red signs with Chinese calligraphy reading “PIPES AND LAMPS ALWAYS CONVENIENT”, served both Chinese and a growing white clientele, initially from the urban underworld and later from more “respectable” circles.

Opium use, initially a habit primarily among Chinese immigrants, became increasingly prevalent among the white population in the US by the 1870s and 1880s. This growing association, fueled by existing xenophobia and racism, contributed to a negative perception of Chinese immigrants, often leading to their criminalization. Discrimination and stereotypes: Anti-Chinese sentiment flourished during this period, stemming from economic competition, cultural differences, and outright discrimination against Chinese immigrants. Chinese laborers, often working for lower wages to support families back home and pay off debts, faced resentment from non-Chinese workers. This, coupled with the association of Chinatowns with gambling, prostitution, and opium use, led to racist campaigns that portrayed Chinese immigrants as corrupting society.

Concerns about Chinese opium smoking were exploited by those who sought to restrict Chinese immigration. This anti-Chinese sentiment eventually culminated in the Chinese Exclusion Act of 1882, which explicitly restricted immigration based on nationality and was not repealed until 1943.

Some Chinese crime organizations, known as Tongs, played a role in the illicit activities within Chinatowns, including the opium trade. Originally formed as benevolent associations to assist Chinese immigrants, some Tongs became involved in criminal enterprises like operating opium and gambling dens.

It’s important to remember that the narrative of Chinese immigrants and opium in the late 1800s is complex and multifaceted, entangled with issues of immigration, discrimination, and the social and economic conditions of the time.

Nearly 2 decades later, the war on drugs plays on. Leadership still tries to blame China, for opium, but the narrative shimmers to and fro, to include Afghan poppy fields, and now Latin American producers, shoppers and street dealers.

Somehow, these politically charged, police actions are oft times built upon a ting of racial animosity, leading to misdirected conclusions that never seek to point a finger at our own users, addicts and junkies, seeking the thrill of the high. Is it the enemy abroad, the enemy within, or the leadership, using both to maintain their power base. We criminalize, deport and incarcerate dealers and those found in possession, rather than develop mental, medical or diversionary programs to stem the desire to use.
 

Play ball.


Anti-Crypto Corruption Week

Democrats Launch “Anti-Crypto Corruption Week” in Opposition to GOP-Backed Legislation


Washington, D.C., July 15, 2025 — Democrats on the House Financial Services Committee, led by Ranking Member Maxine Waters (D-CA) and Congressman Stephen Lynch (D-MA), have announced a coordinated effort dubbed “Anti-Crypto Corruption Week” in direct response to a trio of Republican-backed crypto bills moving rapidly through Congress. The legislative package, which includes the “CLARITY Act,” the “GENIUS Act,” and a bill opposing the establishment of a central bank digital currency (CBDC), has drawn fierce opposition from Democratic lawmakers who argue that the proposals would strip away key protections for consumers and investors, while opening the financial system to abuse.


The lawmakers argue that these bills could significantly weaken the federal government’s ability to monitor digital assets, provide regulatory oversight, and prevent financial crimes. According to public statements from Waters and Lynch, the proposed laws would not only embolden crypto-based fraud but also normalize what they have described as a series of ethically compromised ventures tied to President Trump and his associates.


“These bills, in their current form, would do nothing to protect the average investor,” said Waters in a press statement. “Instead, they would legitimize an ongoing pattern of abuse and self-enrichment using crypto schemes that have reportedly generated over $1.2 billion in personal profit for the former president and his inner circle.”

Among the key concerns raised by Democrats is the lack of consumer protection language within the bills. Critics have pointed to the failure of the “CLARITY Act” to address issues like investor disclosure, anti-money laundering safeguards, and protections for users of stablecoins — digital tokens that are often marketed as safer alternatives to more volatile cryptocurrencies.


Congressman Lynch emphasized that beyond domestic implications, these bills could also compromise national security and global financial leadership. “The Anti-CBDC Surveillance State Act, for example, could significantly restrict research and development into a U.S. central bank digital currency,” Lynch warned. “Meanwhile, international competitors such as China continue to advance their own digital currency frameworks, potentially giving them an upper hand in global economic affairs.”


The timing of the legislative push by Republicans has also drawn criticism, coming just days after what Democrats have called “one of the largest billionaire tax giveaways in U.S. history.” According to Waters, the crypto bills represent a continuation of a broader effort to deregulate financial markets in a way that benefits a small group of politically connected insiders at the expense of the broader public.


In response, House Democrats are pursuing a multi-pronged strategy during Anti-Crypto Corruption Week. That strategy includes continued public opposition, the introduction of counter-legislation, and the use of procedural tools to stall or block further advancement of the GOP-led crypto package.


Among the Democratic initiatives is the “STOP Trump in Crypto Act,” which would prohibit current and former federal officials, including members of Congress, from personally profiting from crypto-related ventures while in office or immediately thereafter. The bill was introduced ahead of a private fundraising dinner hosted by the former president, which reportedly featured the promotion of a new meme-based cryptocurrency tied to his political brand.


This latest effort builds on a series of actions taken by Committee Democrats throughout the year. In a recent 13-hour markup session, Waters and her colleagues offered over 30 amendments to a Republican-backed stablecoin bill. All were rejected by the majority. The Democrats also staged a walkout of a joint Financial Services-Agriculture Committee hearing, citing the refusal to include provisions addressing executive-level conflicts of interest.


Following that protest, Waters led a separate Democratic-only hearing focused on what she described as a growing pattern of financial misconduct in the crypto industry, specifically tied to individuals closely aligned with the former president. Democrats later used a procedural tactic known as a “Minority Day Hearing” to convene a second round of expert testimony, further highlighting their concerns over the crypto market structure bill.


Behind the scenes, Waters hosted a page-by-page review of the CLARITY Act with subject matter experts in ethics, securities law, and national security. That session, open only to Democratic members of the committee, was intended to underscore what critics see as dangerous loopholes in the bill that could be exploited by public officials or politically connected individuals.


The opposition by Democrats is rooted in a longer-term strategy initiated under Waters’ tenure as committee chair. In 2019, she created the House’s first Task Forces on Financial Technology and Artificial Intelligence. These groups laid the foundation for the Digital Assets Working Group, which has since conducted extensive dialogue with regulators, industry stakeholders, and consumer advocates. Across two Congressional sessions, the task forces held 22 hearings, examining how digital assets could be regulated without compromising consumer protection or national security.


As debate intensifies in the days ahead, Committee Democrats appear poised to continue their efforts to reframe the conversation around digital assets. “The stakes for consumers, investors, and our democracy could not be higher,” said Waters.


House Republicans, however, remain committed to passing the crypto legislation, touting it as a means to promote innovation and reduce regulatory uncertainty for emerging financial technologies.


The legislative fate of the bills remains uncertain as the Democratic-led opposition continues to gain visibility through hearings, public statements, and proposed countermeasures.


Post Note:

The dangers of cryptocurrency include extreme price volatility. The blood curdling, unexpected and unexplainable, dips in cryptocurrency ledgers are what democrats are warning of. Although the allure of equally unexplained recoveries continue to captivate investors. Still it is the lack of regulation, meaning fewer investor protections and greater security risks like hacking and fraud, and the irreversibility of transactions, making it hard to recover lost funds that should inspire more guard rails and government oversight. If you should lose your private key, you will most likely permanently lose your total investment.

As they say on these streets

“Ain’t no hollar back!”


Play Ball.


Downpayment Toward Equity Act of 2025  

Congress Proposes $100 Billion Boost to First-Generation Homeownership Through Downpayment Toward Equity Act of 2025


WASHINGTON, D.C. — A comprehensive effort to ease access to homeownership for first-time, first-generation homebuyers is underway in Congress through the Downpayment Toward Equity Act of 2025, a bill proposing $100 billion in federal assistance for housing-related costs.

Spearheaded by House Financial Services Committee Ranking Member Maxine Waters, along with Congressman Al Green, Congresswoman Ayanna Pressley, and Congresswoman Sylvia Garcia, announced reintroduction of the Downpayment Toward Equity Act. The legislation is aimed at narrowing the wealth gap and stabilizing long-term economic outcomes for millions of American households.

In the House of Representatives, the bill was introduced on July 16, 2021, as H.R. 4495 by Rep. Maxine Waters. It made its way to the Senate, and it was introduced on September 30, 2021, as S. 2920 by Senator Raphael Warnock.

Though it has experienced a bumpy ride the legislation addresses one of the largest financial barriers facing aspiring homeowners today: the upfront costs associated with buying a home. These costs, including down payments and closing fees, have become increasingly prohibitive as home prices and mortgage rates have surged over the past four years. As of mid-2025, the 30-year fixed-rate mortgage stands at approximately 7%, while average home prices have risen nearly 50% since May 2020.


While overall mortgage originations hit record highs in 2020 and 2021 during a period of low interest rates, many creditworthy individuals—particularly those lacking inherited wealth—were unable to enter the market. Between 2023 and 2024, the share of first-time homebuyers dropped to a historic low of 24%, while the average age of first-time buyers climbed to 38. These trends reflect a tightening of access to homeownership at a time when housing remains the principal source of household wealth in the United States. In 2024, homeowners held over 40 times the median net worth of renters.

The Downpayment Toward Equity Act seeks to reverse this trend by offering targeted financial assistance. Eligible buyers may receive up to $20,000 in aid, with additional funding—up to $25,000—for individuals identified as socially and economically disadvantaged. The bill stipulates that recipients must be both first-time and first-generation homebuyers, with no ownership in the past three years and no parental history of homeownership during that same period. Former foster youth who meet income thresholds also qualify.


Income eligibility is capped at 120% of the Area Median Income (AMI), with exceptions allowing for up to 180% AMI in high-cost housing markets. Qualified recipients must intend to purchase an owner-occupied primary residence, which may include one- to four-unit homes, condominiums, cooperatives, or manufactured homes.


Funds would be administered through the Department of Housing and Urban Development (HUD), which would allocate 75% of funds to states based on a formula considering population, local home prices, and homeownership disparities. The remaining 25% would be distributed on a competitive basis to eligible organizations, including some community development and financial institutions.


To ensure long-term success and responsible homeownership, the bill includes a mandatory housing counseling requirement. HUD-approved counseling agencies would receive 5% of the total appropriation to help prospective homebuyers complete education programs. In cases where counseling capacity is limited, participants can fulfill the requirement through alternative education options. Applicants denied financing after receiving commitment letters would be referred for further assistance and requalification.


Eligible mortgage types include loans backed by federal entities such as Fannie Mae, Freddie Mac, FHA, USDA, and VA, as well as HUD’s Section 184 program. These provisions are intended to streamline access for buyers using mainstream, federally backed mortgage products.


HUD would also be required to submit annual performance reports to Congress, measuring the bill’s impact on homeownership trends and administrative effectiveness. Up to 1% of total funding is set aside to build state and local capacity to manage and implement program requirements. States may use up to 5% of their allocated funds for administrative expenses and training.


A key provision of the bill authorizes HUD and the Department of Justice to conduct studies that examine compelling interest in providing aid to specific disadvantaged groups, with recommendations that could influence how funds are allocated in future years.


Support for the legislation spans a wide array of housing, lending, and community organizations, including the Mortgage Bankers Association, National Housing Conference, Habitat for Humanity International, and the National Association of Realtors. Additionally, numerous local and regional housing advocacy organizations have endorsed the bill, highlighting its potential to provide critical assistance in underserved areas.


The Downpayment Toward Equity Act is positioned as both a practical and strategic response to widening gaps in housing access and personal wealth accumulation. By reducing entry costs, the legislation aims to offer more Americans the opportunity to achieve homeownership—a key driver of long-term financial stability. If enacted, the $100 billion in authorized funding will remain available until fully expended, ensuring sustained support for eligible buyers in the coming years.


While the bill’s future depends on the legislative process and budget negotiations in Congress, its supporters argue that it represents a necessary step to recalibrate a housing market increasingly defined by exclusionary barriers and rising costs. The measure is currently under committee review, with further debate expected in the coming months.


Apartheid Refugee Resettlement

So under their stated mandates, it seems that Elon Musk,Trump, the GOP congress and DOGE did not halt any of the following services under the category of waste, fraud, and abuse.

Refugees resettled in the United States, including those from South Africa under the “Mission South Africa” program, typically receive a range of services designed to help them integrate and achieve self-sufficiency. This assistance is primarily managed by the U.S. Department of State’s Bureau of Population, Refugees, and Migration (PRM) and the Department of Health and Human Services’ Office of Refugee Resettlement (ORR), working with various non-profit resettlement agencies.

Here’s a breakdown of the kind of resettlement assistance provided:

Initial Resettlement (First 3 months – Reception and Placement Program):

* Airport Reception: Refugees are met by staff or volunteers from a local resettlement affiliate, private sponsors, or family/friends upon arrival.

* Housing: Assistance in securing initial housing, which is often furnished.

* Basic Needs: Provision of a one-time initial resettlement money (e.g., $900 per person) to help with immediate expenses like security deposits, transportation, food, and clothing.

* Cultural Orientation: Information and guidance on life in the U.S., including laws, customs, and community resources.

* Access to Services: Help with:

* Applying for Social Security cards.

* Registering children for school.

* Accessing medical care and health screenings.

* Applying for federal benefits they may be eligible for (e.g., Refugee Cash Assistance, Refugee Medical Assistance).

* Connecting with employment services.

* English language training.

Longer-Term Assistance (Beyond 3 months):

* Refugee Cash Assistance (RCA): For those not eligible for other forms of cash aid (like Temporary Assistance for Needy Families – TANF), RCA provides temporary financial assistance for basic needs (food, shelter, transportation). This is often linked to employment services. The duration of RCA can vary, but generally, it’s for up to 12 months from their date of admission.

* Refugee Medical Assistance (RMA): For those not eligible for Medicaid, RMA provides health insurance coverage. Similar to RCA, the duration of RMA can vary.

* Matching Grant (MG) Program: An alternative to RCA, this program focuses on early self-sufficiency through intensive case management and employment services. The goal is to help refugees become economically self-sufficient within 240 days of arrival without relying on public cash assistance.

* Employment Services: These are crucial for long-term self-sufficiency and include:

* Job training and preparation.

* Assistance with job search, placement, and retention.

* Help with building resumes and interview skills.

* English Language Training (ELT): Classes to help refugees improve their English skills, which is vital for integration and employment.

* Social Adjustment Services: Connecting refugees with community-based organizations and support networks to help them adjust to their new environment.

* Specialized Programs: ORR also funds programs for vulnerable populations, such as victims of torture, and provides services like trauma assistance, childcare, and transportation assistance.

The specific “Mission South Africa” program expedited the processing of refugee applications for white South Africans. While the underlying claims for this program are controversial, the individuals granted refugee status under it would be eligible for the standard resettlement assistance provided to all refugees in the U.S.